Wiring money to an overseas manufacturing partner is fundamentally an act of trust underpinned by paperwork. For most importers, the initial telegraphic transfer deposit represents between twenty and fifty percent of the total purchase order value. It is the exact moment commercial exposure shifts from theoretical negotiation to real financial liability. Once capital clears an offshore intermediary bank and lands in mainland China or Hong Kong, recovering it without formal legal standing or physical leverage is remarkably difficult. Importers who move too quickly through this juncture frequently mistake courteous email communication and polished digital sample photos for genuine operational capability.
A disciplined procurement process requires buyers to systematically identify china supplier red flags before instructing their treasury or finance department to release funds. The presence of supplier warning signs does not automatically mean an enterprise is an outright criminal syndicate. More often, it indicates a structural mismatch between what the sales representative promises and what the underlying corporate entity can legally, financially, and operationally deliver. Distinguishing between ordinary administrative clumsiness and deliberate deception requires looking past polished English correspondence and scrutinizing the core legal, financial, and geographical identifiers of the vendor.
Consider a hypothetical scenario common among mid-sized consumer goods brands sourcing injection-moulded enclosures in Guangdong province. An importer based in Frankfurt or Chicago settles on a quote that sits ten percent below regional market rates for tooling and unit pricing. The supplier presents crisp digital renderings, a responsive English-speaking account manager named Kevin, and an ISO 9001 certificate bearing a recognizable logo. Production timelines are tight, and Kevin insists that raw polymer costs in Dongguan are set to jump at the end of the week. He issues a proforma invoice requesting a thirty percent tooling deposit to lock the quote. The bank details on the proforma invoice, however, direct the transfer not to the precision plastics factory named in the commercial correspondence, but to an unlisted commercial trading entity registered in Hong Kong. The buyer signs off, sends seventy-five thousand dollars, and waits. Three months later, tooling updates stop, the email domain begins bouncing messages, and the physical address listed on the invoice turns out to be a shared desk in a commercial office tower that vacated six months prior.
Catching these patterns early requires systematic attention to specific, observable irregularities. A buyer should examine four primary structural areas before authorizing any payment instruction:
1. Payee mismatch. The legal entity named on the proforma invoice must match the unified social credit code on the Chinese business license, the enterprise export registration, and the corporate bank account name. When an overseas account manager asks for payment to clear through a personal account, an unrelated domestic intermediary, or an offshore shell company with no demonstrable corporate relationship to the manufacturing site, risk escalates exponentially. While some legitimate domestic factories use licensed foreign trade agents to handle customs clearances and foreign exchange settlements under State Taxation Administration rules, those arrangements must be accompanied by explicit agency contracts and traceable cross-guarantees rather than ad hoc wire instructions sent via PDF.
2. Pressure tactics around raw materials or regulatory windows. Sales representatives frequently manufacture artificial urgency, claiming that resin, copper, or aluminium ingot prices in Foshan or Ningbo will rise unless the deposit arrives within forty-eight hours. While material indices fluctuate on the Shanghai Futures Exchange, established factories hold buffer stock or formal rolling options; they do not condition basic commercial viability on a two-day telegraphic transfer window. Urgency designed to shorten the buyer's due diligence window is one of the most reliable supplier warning signs.
3. Unverifiable factory addresses. A company claim that it operates ten thousand square metres of fabrication floor must correspond to a verifiable industrial land-use parcel or registered factory tenancy contract. Discrepancies between an administrative office address listed on the National Enterprise Credit Information Publicity System and the purported manufacturing address provided on a bill of materials frequently reveal an unauthorized trading intermediary operating without production equity or direct shop-floor control.
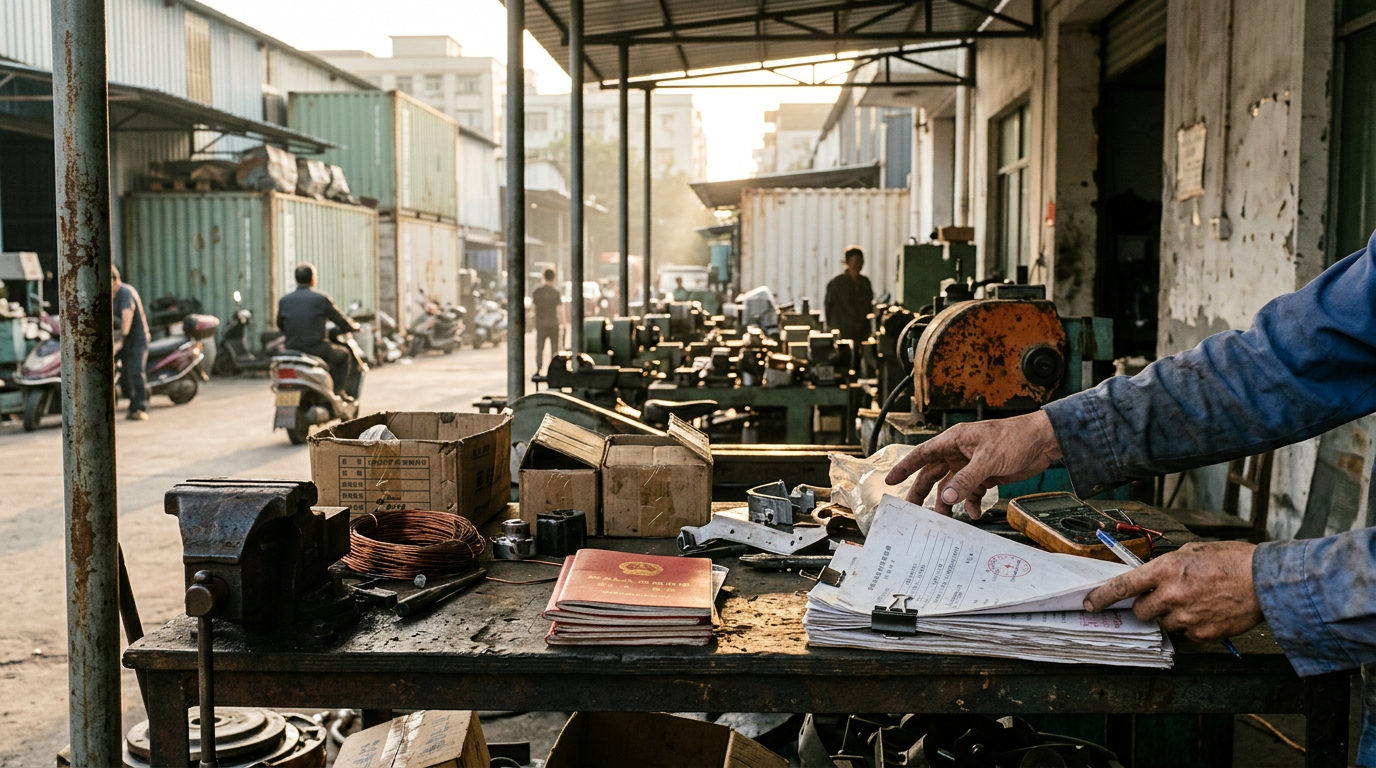
4. Inconsistent official documentation. In Chinese corporate administration, discrepancies between the registered business scope, the capital contribution schedule, the unified social credit code, and supplementary documents like environmental impact assessment approvals or fire safety filings point to internal administrative distress, recent corporate restructuring, or outright document fabrication.
When evaluating these signals, buyers must understand what a single red flag does and does not mean. An isolated discrepancy does not automatically prove an intention to defraud. China has millions of small and medium-sized private manufacturing operations, many run by technical founders whose primary focus is machine throughput rather than international corporate governance. A missing English translation on a test certificate, an outdated administrative registration address following a relocation from Bao'an to Guangming, or a minor spelling error on a proforma invoice can simply reflect internal administrative gaps. These operational errors are warnings to pause, verify, and clarify; they are not instant proof of bad faith.
Conversely, the total absence of overt red flags in digital correspondence does not confirm that a factory is competent or stable. Fraudulent operations and financially distressed workshops have learned to present clean digital facsimiles, complete with forged business licenses, borrowed ISO certifications, and polished presentation decks. True due diligence is not a superficial checklist of document presence; it is the cross-verification of public corporate filings, direct bank registration records, and physical site operations against what the commercial contract specifies.
To resolve these uncertainties safely, every importer should execute a disciplined sequence before sending any funds. First, obtain the supplier's official business license in original Chinese script, extract the eighteen-digit unified social credit code, and pull the direct public enterprise record from the market regulation bureau database. Verify that the registered legal representative, shareholder structure, and registered capital status align with your commercial interlocutors. Second, require the vendor to execute a formal, bilingual manufacturing agreement under clear Chinese jurisdiction before issuing the proforma invoice, ensuring that bank account details, Incoterms 2020 definitions, and accepted non-destructive testing benchmarks are legally integrated.
Third, cross-reference the exact payee name on the wire instruction against the enterprise credit record. If the payment directs to a third-party exporter or domestic agent, require a tripartite agreement countersigned and stamped with the factory's official red company seal, or company chop. Finally, commission an independent physical site check or basic commercial investigation before transferring tooling or raw material deposits. An on-the-ground visit confirms whether the automated SMT lines, CNC machining centres, or cleanrooms described in promotional decks actually exist, belong to the vendor, and have the active operating capacity to fulfill the order.
A valuable operational distinction to remember is that a factory audit verifies physical production systems and quality infrastructure, whereas a supplier verification verifies legal standing, corporate solvency, and ownership legitimacy. An operation can maintain clean, well-managed injection presses and disciplined assembly workers on the shop floor while sitting on the verge of asset freezing, severe debt enforcement, or administrative dissolution under local civil court judgments. Verifying machinery without examining corporate standing leaves your balance sheet exposed, just as reviewing paperwork without physical site confirmation leaves your delivery schedules exposed to unannounced third-party subcontracting.
Before wiring a deposit to an unfamiliar supplier in mainland China, establish clear empirical proof of who holds your capital and where your goods are actually made. Procubility provides independent, buyer-funded supplier verification, corporate investigations, and factory audits across China's major industrial hubs, delivering the documented evidence overseas procurement teams need to protect their capital before issuing payment instructions.